
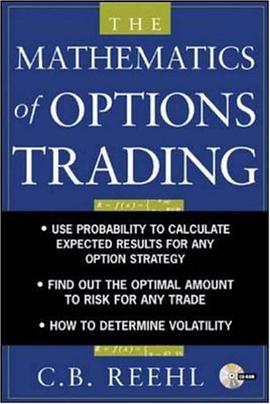

具体描述
This title offers market-tested guidelines to understand the math and determine the profit potential of each option trade. Successful option trading requires that you understand and know how to use the mathematics underlying option prices. "The Mathematics of Options Trading" focuses on that math, providing you with the knowledge you need to both determine expected results of an option trade and calculate the optimum position size before committing capital. Based on never-before-published work and research, this straightforward book includes: clear-cut explanations of volatility and time to expiration - the two most important concepts for option traders; formulas and examples for calculating profit profiles of naked and covered options, combinations, spreads, synthetics, and more; and, the Reehl Option Trader CD - with programs that immediately analyze profitable opportunities using numerous different strategies."The Mathematics of Option Trading" explores dozens of formulas and techniques for analyzing option trades, as well as for understanding the odds of those trades, based on mathematical probabilities. It shows you how to work the numbers to take advantage of favorable opportunities as they present themselves, while at the same time making the necessary moves to reduce risk at every step. Trading options is a meticulous and exacting undertaking that is fraught with risk. One way to achieve more consistent profitability is to gain a working knowledge of the mathematics and analyze the profit/loss profiles of each trade before putting your trading capital on the line. "The Mathematics of Options Trading" focuses on the formulas and know-how you need to remove much of the guesswork from trading options.This in-depth trading manual provides you with the mathematical sophistication required for successful options trading, taking the mystery out of the math and making it both understandable and usable. Its comprehensive coverage includes: formulas for developing profitable option strategies, including algebraic derivations, explanations and examples; basic combinations - covered calls and puts, protective puts, spreads, straddles, and strangles; strategy variations in which the number of options involved is important, including ratio spreads, backspreads, and butterfly spreads; calculation of mathematical expectation - the product of the value of an event and the probability of the event's occurrence; and, historical volatility - its calculation, use with the Black-Scholes option pricing model, sources for volatility information, and more.It also includes: the Greeks - Delta, Gamma, Vega, Theta, and Rho, with calculations and examples; and, other valuable concepts, including moving averages, first and second order equations, search algorithms, the put/call ratio, the central limit theorem, and more. Before you can be consistently successful as an option trader, you must first consider the possible outcomes together with their associated probabilities to always be aware of the odds of success. "The Mathematics of Options Trading" explains the mathematics required to achieve that goal, and how to dramatically improve the profit potential of trade selection. The powerful accompanying CD includes: Expectation.exe - produces results for a single trade for any strategy covered in the book, both onscreen and on a printed report; and, DailyCheck.exe - produces a printed report covering all example strategies for options on a given underlying instrument.
作者简介
目录信息
读后感
用户评价
这本书的装帧和设计真是让人眼前一亮。拿到手的时候,那种厚重感和纸张的质感就给我留下了深刻的印象,完全符合一本专业金融书籍应有的分量。封面设计简约而不失专业性,那种冷静的蓝色调和清晰的字体排版,透露出一种严谨治学的态度。内页的印刷质量也相当出色,字迹清晰,排版疏密得当,长时间阅读下来眼睛也不会感到疲劳。尤其值得称赞的是,书中对图表和公式的呈现方式。那些复杂的数学模型和金融图示,被清晰、准确地还原在纸面上,没有出现任何模糊不清或者排版混乱的情况,这对于理解那些抽象的金融概念至关重要。可见作者和出版方在细节处理上是下了大功夫的,这种对物理载体的尊重,本身就为阅读体验增添了许多分数。我常常觉得,一本好的专业书籍,不仅内容要扎实,它触手可及的质感也同样重要,这本书在这方面做到了近乎完美。
评分读完这本书后,我感觉自己的思维方式发生了一种微妙但重要的转变,它让我从一个“市场参与者”升级为一个“市场结构分析师”。书中对于连续时间金融模型中极限和收敛性的处理,那种对理论边界的敬畏感,深深地感染了我。它不只是教你如何计算希腊字母,而是教你如何理解这些衡量指标背后的随机过程本质。这种从微观到宏观,从局部到整体的逻辑串联能力,是极其宝贵的。这本书没有提供任何捷径,它要求读者投入时间去理解那些基础的公理和假设,但一旦你完成了这个过程,你所获得的,是一种能够应对未来任何金融创新挑战的底层能力。这是一本值得反复研读,并且每次重读都能发现新东西的里程碑式的著作。
评分阅读这本书的过程,感觉就像是进入了一个精心构建的逻辑迷宫,但每一步都有清晰的指引,最终能通往豁然开朗的境界。作者在叙事节奏的把握上显示出了高超的技巧,从基础的概念铺陈开始,逐步搭建起复杂的理论框架,绝不急于抛出那些深奥的公式,而是循序渐进地引导读者适应这种数学化的思维方式。比如,在讲解波动率模型时,他没有直接堆砌复杂的偏微分方程,而是先用非常直观的例子来阐述模型背后的经济学直觉,然后再引入数学工具进行精确描述,这种“先感性认识,后理性分析”的处理方式,极大地降低了理解门槛。读完一个章节,我常常能感受到一种扎实的、知识点被牢牢掌握的充实感,而不是那种一知半解的浮躁感。
评分这本书最大的魅力,或许在于它毫不妥协地拥抱了数学的严谨性,同时又没有将读者拒之门外。我以前接触过一些金融衍生品教材,它们要么过于侧重应用而牺牲了理论深度,要么就是数学推导过于冗长枯燥,让人望而却步。然而,这本书找到了一个极佳的平衡点。它将概率论、随机过程这些硬核工具无缝地整合到期权定价和风险管理的应用场景中,使得每一个数学步骤都显得“有意义”,而不是为了展示数学能力而存在。每当遇到一个关键的推导时,作者总会适时地给出一段文字解释,阐明这一步的金融意义,这种“翻译”工作做得非常到位。这让我不再是机械地套用公式,而是真正开始思考“为什么是这个公式”,这对于提升我的交易策略的底层逻辑构建能力有深远的影响。
评分对于实战交易者而言,这本书提供了一种超越市场噪音的视角。很多交易书籍侧重于“如何操作”和“市场心理”,但这本书却深入到了“定价的本质是什么”这个核心问题。它并没有直接给出“买入或卖出”的建议,而是提供了一套完整的、基于数学原理的评估工具箱。例如,关于套利边界的讨论,那种对市场效率的深刻洞察,让我对当前市场上的定价偏差有了更冷静的判断。我发现,当我能够用书中的框架去解构一个复杂衍生品结构时,那种对不确定性的掌控感是任何“快速致富秘籍”都无法给予的。这本书更像是一张去往金融世界深处的“地图”,指引着我们理解市场的内在运行机制,而不是仅仅在表面上追逐波动。
评分 评分 评分 评分 评分相关图书








本站所有内容均为互联网搜索引擎提供的公开搜索信息,本站不存储任何数据与内容,任何内容与数据均与本站无关,如有需要请联系相关搜索引擎包括但不限于百度,google,bing,sogou 等
© 2026 book.wenda123.org All Rights Reserved. 图书目录大全 版权所有